
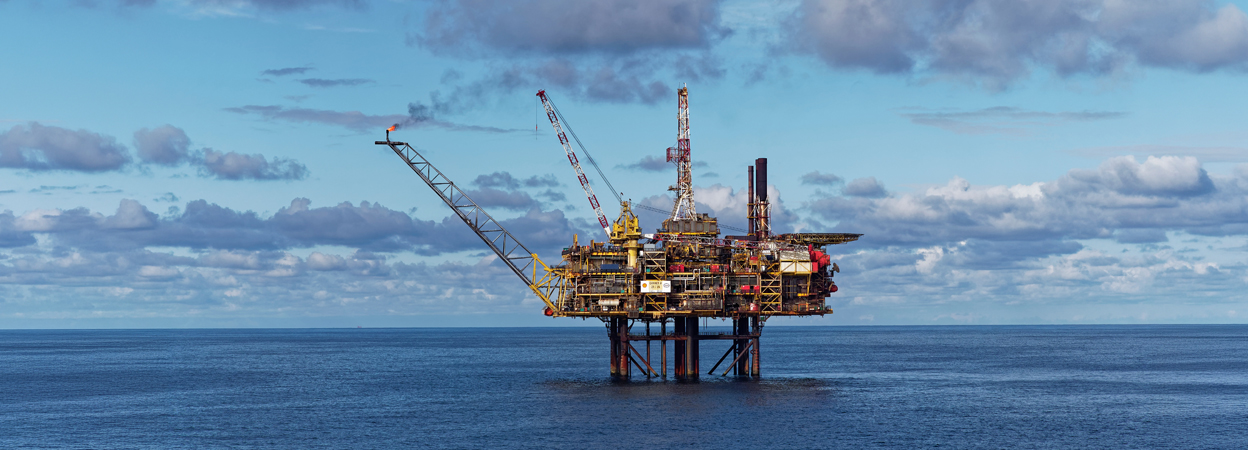
The latest results from five international energy companies highlight a subsurface sector focused on selective high-impact exploration, major gas developments and partnerships to share risk. Production trends also show how acquisitions, project start-ups and mature-field decline are reshaping portfolios.
TotalEnergies reports discoveries and advances four gas projects
TotalEnergies’ production averaged 2.474 million barrels of oil equivalent per day (boe/d) in Q3, up 3% from the previous quarter. The company said project ramp-ups supported production, while the impact of the Middle East conflict averaged around 5% of its total output.
The exploration update included TotalEnergies’ completed entry into Namibia’s PEL83, which contains the Mopane discovery, and participation in three discoveries: Grimsnes in Norway, and Block 0 and Violeta 4 in Angola. Final investment decisions were also taken on four gas projects: Cronos in Cyprus, Ima in Nigeria, Umm Shaif Gas Cap in the UAE and Absheron Phase 2 in Azerbaijan. TotalEnergies says all projects supporting its target of production growth above 3% a year to 2030 are now in execution.
A three-year partnership with Mistral will develop AI models for exploration and reservoir engineering, bringing a technology focus directly into subsurface workflows.
BP advances gas exploration and shares prospect risk
BP reported Q3 upstream production of 2.220 million boe/d, broadly steady quarter on quarter but below the 2.362 million boe/d recorded a year earlier.
Its exploration and development portfolio includes the Loran Phase 2 offshore gas licence in Venezuela, where BP is operator alongside XRG and UCC. The field is estimated to contain 4 trillion cubic feet of recoverable gas resources. BP also agreed to farm down interests in two exploration opportunities while remaining operator: Tupinambá in Brazil’s Santos Basin and the Conifer prospect in the deepwater Gulf of America. The agreements show how partnerships can share exploration risk while allowing BP to retain operatorship.
ExxonMobil strengthens its position in large gas projects
ExxonMobil’s Q3 upstream production was 4.496 million boe/d. Cumulative production has reached 1 billion barrels each at Guyana and Kearl, while PNG LNG has produced 100 million tonnes.
The company assumed operatorship of Papua LNG and agreed to raise its interest in the project to 34%. In Mozambique, it agreed to increase its interest in Rovuma LNG to 50%, where it is already operator. The moves strengthen ExxonMobil’s position in major gas developments. The company also reported approval of the Rose carbon storage project and the start-up of CCS operations at Nucor.
Shell’s production rises with ARC acquisition
Shell reported production of 2.574 million boe/d in Q3, up from 2.455 million in Q2. The increase mainly reflected its acquisition of ARC Resources, which added around 370,000 boe/d of liquids and gas production. Shell also took a final investment decision on LNG Canada Phase 2, which is designed to double the facility’s capacity from 14 to 28 million tonnes of LNG per year.
Shell completed the sale of its interests in the Na Kika platform and associated Gulf of America fields, including the Coulomb tieback. Its results also cited higher well write-offs as a factor in lower upstream earnings compared with Q2.
Chevron reports Angola discovery and new exploration agreements
Chevron’s Q3 report highlighted an offshore oil and gas condensate discovery in Angola’s Lower Congo Basin, as well as a new exploration agreement with Libya’s National Oil Corporation in the Sirte Basin. The company also expanded its acreage in Venezuela and said its joint ventures plan to invest $7 billion over five years, aiming to more than double production to approximately 600,000 barrels per day.
The Angola discovery at well 105-4X encountered a hydrocarbon column of more than 600 metres, including over 90 metres of net pay in the Pinda reservoir. Chevron said it will assess the discovery for a potential tie-back to nearby facilities, linking high-impact exploration with existing infrastructure. Chevron
What the results signal for subsurface teams
Across the five companies, exploration remains part of the resource-replacement strategy, but it is increasingly tied to execution, infrastructure and capital discipline. Namibia, Angola, Norway, Brazil, Venezuela, Libya and the Gulf of America feature in the latest activity. Meanwhile, major gas and LNG projects are progressing in Cyprus, Nigeria, the UAE, Azerbaijan, Papua New Guinea and Mozambique.
For geoscientists, the quarter’s clearest themes are the continued pursuit of high-impact prospects, the use of farm-downs and joint ventures to manage exploration risk, and the importance of integrating discoveries with existing facilities or large-scale gas developments. AI is also entering the exploration and reservoir-engineering toolkit, while production figures underline the influence of project ramp-ups, acquisitions and mature-field decline.

